Student-loan relief for an upfront fee: separate real help from the sales pitch
A deadline, a government-looking seal, and a promise to erase debt can make a paid service look official. Verify your loan and servicer before paying or sharing access.
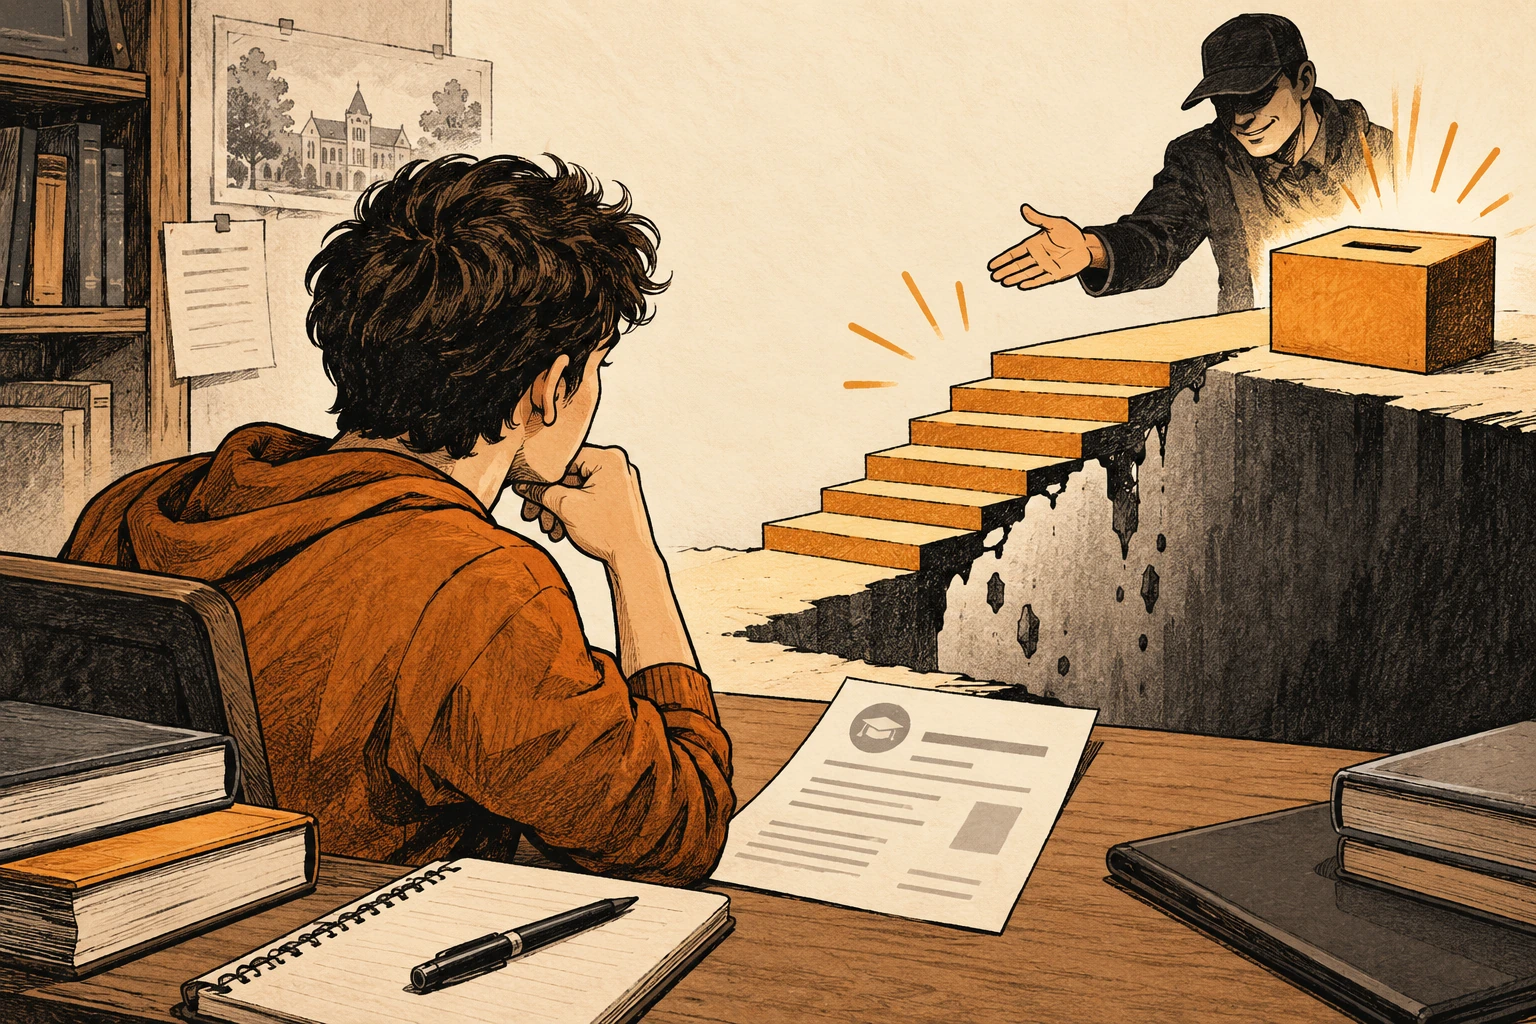
The voicemail sounds as though someone has already reviewed your file. Your loans have been “flagged for relief,” the enrollment window is closing, and a specialist can finish the process if you pay a processing charge today. For someone worried about repayments, that can feel less like a sales call than a chance to escape a problem that has followed them for years.
Start with a distinction: an offer of help is not a decision by the government or your loan holder. The person making the call does not gain authority over your loans by knowing your name, approximate balance, or school.
This article concerns US student loans, especially federal loans. It does not assess eligibility for a particular repayment, forgiveness, discharge, or default-resolution option. Those rules and availability can change. Check your actual loan type and the current official information before making a decision.
Rebuild the picture from your own account
Open StudentAid.gov independently and identify the federal loans and servicer shown in your account. Use the contact information supplied through that official route. For private loans, use the lender or servicer details on an established statement or account, not a caller’s claim that all education debt is handled by one program.
Write down what you need help with. Is the monthly payment unaffordable? Are you unsure who services the loan? Is there a default notice? Are you trying to understand an employment-related forgiveness route? A specific question is harder to replace with a vague promise to “wipe everything.”
Federal Student Aid’s scam-prevention guidance explains that borrowers can obtain help from their federal servicer without paying a third-party enrollment fee. It also warns against sharing StudentAid.gov credentials. Paying an unaffiliated company does not give it special access to a forgiveness decision.
Federal and private loans do not share every rule or relief option.
A paid document service is not automatically your servicer or a government agency.
Do not give a caller your account password or approve changes you do not understand.
What is the company actually selling?
Some businesses charge for completing forms or providing administrative assistance. The existence of a fee alone does not establish every element of fraud. But the service should be described honestly, with a clear identity, scope, price, and explanation of what you can do directly.
Ask whether the company is your loan servicer, an independent adviser, a document-preparation service, or something else. Ask which action it proposes and who makes the final decision. A company that cannot distinguish its own fee from a payment toward your debt has not given you enough information to consent.
Do not accept a verbal promise that the fee “goes toward the loan” without checking where payments will be credited. Compare your actual servicer account, not the company’s private dashboard. A receipt from a relief business is not proof that a loan payment or application reached the correct recipient.
Translate the pitch into questions
| Sales claim | Question to ask through an official route | Risk if you skip the check |
|---|---|---|
| “You are already approved” | Which program and which official decision confirms that? | Treating marketing as an eligibility determination |
| “Enrollment closes today” | Where is the deadline published for my loan and circumstances? | Paying under an invented time limit |
| “Give us your login and we will do it all” | What authorized assistance process exists without surrendering credentials? | Losing control of account settings and applications |
| “Our fee replaces your next payment” | Has the actual servicer confirmed any change to what is due? | Paying the helper while the real obligation remains |
| “Only our company can access this option” | Is the option available directly through official channels? | Buying exclusivity that does not exist |
You can decline to answer sensitive questions until the caller explains the service. A legitimate need for information does not make every collection channel legitimate.
Do not let policy uncertainty become a sales tool
Student-loan headlines can be confusing. A proposal, court decision, administrative announcement, application opening, and individual approval are different events. A social-media summary may omit which borrowers or loans it covers.
If a caller cites breaking news, locate the official announcement yourself and check its date. Ask whether it describes a current process, a future change, or litigation. Do not pay to reserve a place in a program merely because someone says the news will disappear from public view.
Avoid relying on an old screenshot of repayment options. Use the current account and official guidance. This article deliberately does not list a supposedly universal “best plan,” because the appropriate option depends on loan details and the rules in force when you apply.
If your loans are in default
The word “default” adds urgency and can make a paid rescue sound essential. First confirm the status through your actual account. Federal Student Aid’s default and collections FAQs explain official contacts and warn about enrollment, subscription, or maintenance fees charged by outsiders claiming to resolve default.
A real repayment or rehabilitation agreement can involve payments. That is different from paying an unknown company to unlock access to an official process. Ask who receives the money, how it is recorded, and where the agreement can be confirmed independently.
Do not ignore genuine notices while investigating a suspicious caller. Keep deadlines from official correspondence separate from deadlines invented during a sales conversation. If the situation is complex or involves legal proceedings, seek qualified advice appropriate to your jurisdiction rather than relying on a caller who promises an immediate cure.
If you have already signed or paid
Gather the contract, advertisement, emails, receipts, and any authorization you granted. Identify recurring charges as well as the initial payment. Keep a copy before using the company’s cancellation process, and record when you sent the request.
Contact your actual servicer to ask whether any applications, account changes, or third-party authorizations have been submitted. Explain which company you dealt with. Ask how to review or revoke unwanted authority through the proper process. Cancelling a card payment does not necessarily cancel a contract or reverse a loan-account change.
Contact your payment provider about the payment and any recurring authorization. Describe what was promised and what happened. Whether a charge can be stopped or disputed depends on the payment method, timing, and facts; a refund is not guaranteed.
If you disclosed a password, change it through the official account and review recovery details. Replace the same password anywhere else you reused it. Do not let the supposed helper guide the reset while remaining connected to your screen.
An example of a useful call to the real servicer
Rather than asking “is this company good?”, give a concrete description: “A business contacted me saying it can enroll me in a relief option for a fee. I have not confirmed the option in my account. Can you tell me my current loan status, the official options available for this issue, and whether any third-party authorization or application has been added?”
Write down the date, representative or case reference where available, and the answer to each question. If you need time to consider the options, ask how to obtain the information in writing. You do not have to choose a plan during the first conversation simply because the original caller created urgency.
If you are supporting a family member, help organize records and calls with their permission. Avoid taking their credentials or making financial choices on their behalf without appropriate authority. Assistance should restore the borrower’s control, not move it to another person.
Be careful with the promised refund
After a complaint, a new caller may claim to represent a regulator or recovery team. They may know the name of the company you paid. That knowledge does not prove they can recover the money, and an upfront “release” charge is another demand to assess.
The recovery-scam guide explains this second stage. Our recruiter identity-document guide covers a related boundary: genuine administrative processes sometimes require sensitive data, but that does not excuse an unverified collector.
For suspected fraud, use official consumer-protection reporting routes and keep your records private. Do not post account numbers or loan documents in public groups seeking a verdict. You can describe the mechanism without exposing the information another impersonator would want.
The decision that should remain yours
Good assistance makes the loan easier to understand. It tells you what is known, what is uncertain, what action is proposed, and what it costs. It does not require a secret payment, a surrendered password, or blind trust in a deadline that exists only in a voicemail.
You may still have a difficult repayment problem after rejecting a suspicious offer. That is not evidence that the offer was your only chance. Start from the verified account and the real servicer, and make the next decision on information that does not depend on the person selling relief.
Found a factual error or a source that has changed?
Send a correction →