The Mystery-Shopper Check Looks Available. The Gift Cards Can Still Cost You Your Own Money.
Why an available bank balance does not validate a stranger's check, and what to do before or after a supposed shopping assignment asks for gift-card codes.
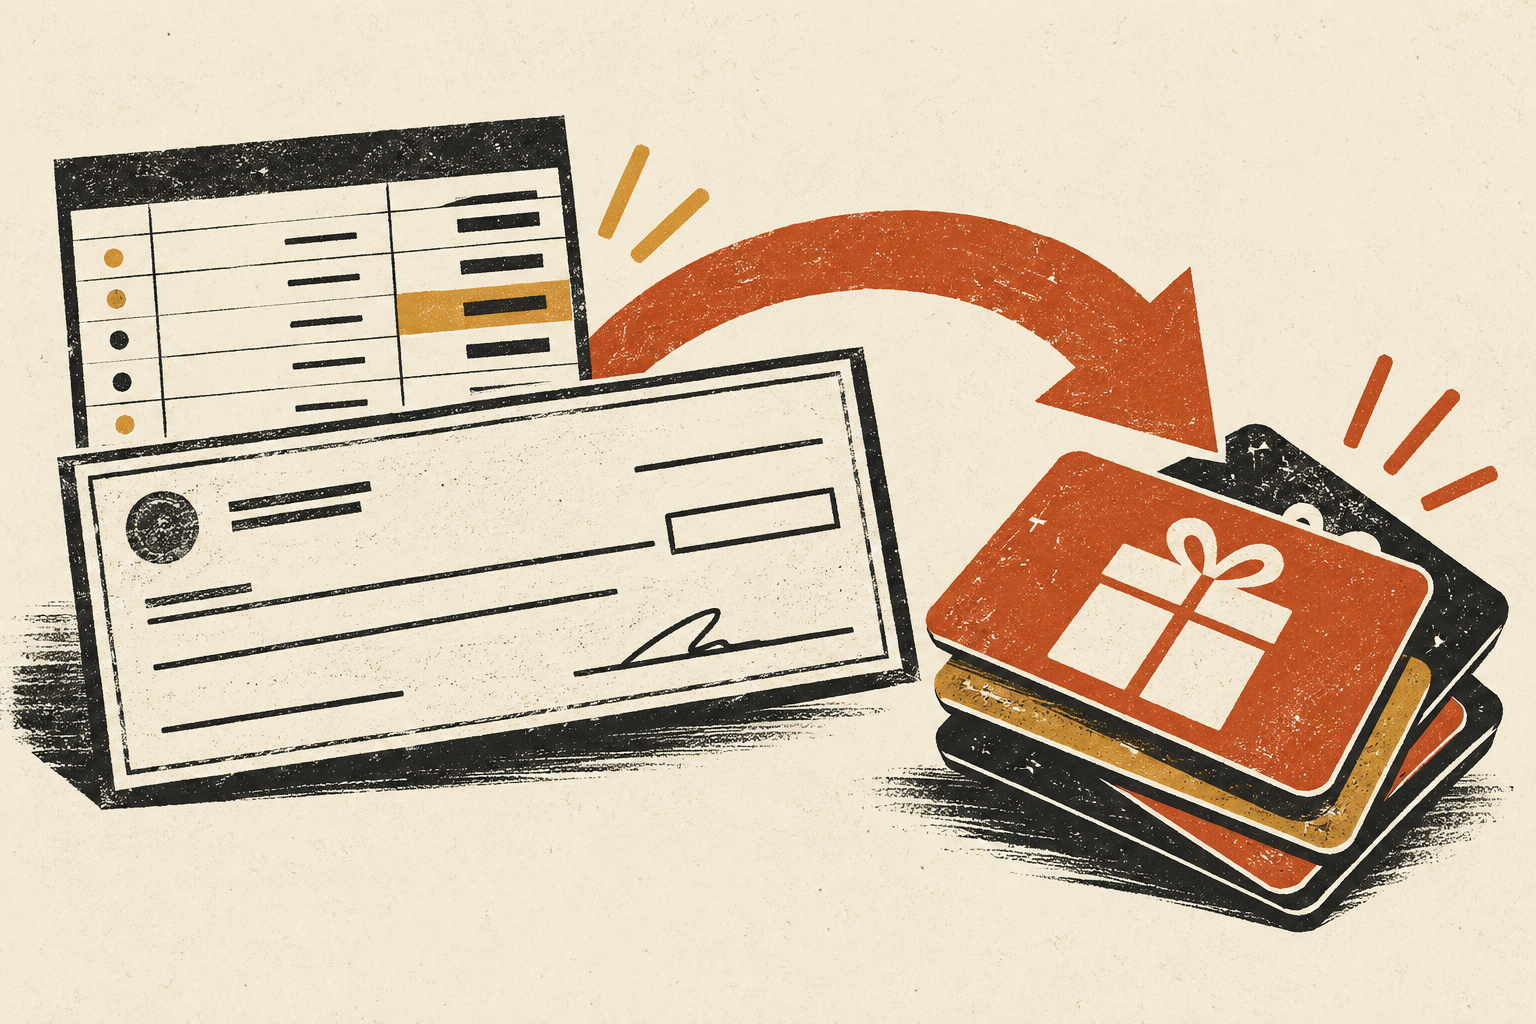
The assignment sounds straightforward: deposit a check, visit a store, buy gift cards, report on the shopping experience, and keep part of the money as your fee. When the bank app shows funds available, the job can appear to have passed its most important test.
That is the dangerous assumption. Money being available to spend is not the same as the check being genuine and finally paid. If you send value away before the check is identified as fraudulent, the loss may land in your own account.
The FTC’s mystery-shopping warning describes this exact combination: a supposed employer sends a fake check, asks for gift-card purchases, and requests the card numbers. The legitimate existence of mystery-shopping work does not validate that assignment.
Follow the two money movements
There is an incoming item, the check. There is also an outgoing payment, the gift-card purchase or transfer. They are not one protected transaction simply because the supposed employer describes them as part of a job.
The outgoing value can be used before the problem with the incoming check is resolved. A later rejection of the check does not automatically retrieve gift-card value already disclosed to someone else.
The FTC’s fake-check guide explains why apparent access to deposited funds can be misleading. Do not rely on a recruiter’s claim that a balance screenshot proves the assignment is safe.
| Stage | What the screen or instruction may suggest | What it actually proves |
|---|---|---|
| Check received | The employer has funded the assignment | A document or image was delivered |
| Deposit accepted | The bank verified the whole arrangement | The bank accepted the item for processing |
| Funds shown as available | The money is permanently safe to spend | The account currently allows access under its funds-availability process |
| Gift-card codes sent | The shopping task is complete | Another person may now be able to use that value |
The report they need is the code, not your customer experience
A real shopping evaluation might ask about wait times, service, product availability, or a purchase experience. In this scam pattern, the decisive request is to transmit spendable card information.
Photographing the back of a card or sending its PIN is not merely documenting that you visited a store. It can transfer control of its value. Do not let an assignment’s survey format obscure what the requested data can do.
A company logo, professional-looking questionnaire, or named retailer does not authenticate the hiring relationship. Verify the employer through independently found details before accepting financial instructions, and do not assume the store named in the assignment is involved.
If the check has not been deposited
Do not deposit it to “see whether it works.” Contact your bank if you need guidance about a suspicious item, and keep the original correspondence for reporting. Do not send the supposed employer a bank screenshot or other account information.
Research the company and the specific job through a route outside the recruitment conversation. A genuine business can be impersonated. Finding that the business exists is only the first check; confirm that it actually offered this work.
The FTC’s mystery-shopping guide also cautions against paying upfront to obtain such work. A request for a registration fee or paid certification is not made safe by a promise that a later assignment will reimburse it.
If you deposited the check but have not spent the money
Explain that you suspect a fake-check job scam, identify the deposit, and ask what to do next. Do not withdraw, spend, or send the amount back to a stranger while the bank investigates.
A message telling you to return an “overpayment” through another service is not a safe cancellation. It introduces a fresh outgoing transaction while leaving the original check problem unresolved.
Ask the bank to clarify the item’s status and any account restrictions or obligations. Keep the conversation reference. Do not treat a generic balance inquiry as equivalent to telling the bank that the deposit may be fraudulent.
If you bought cards but still have the codes
Stop communicating with the supposed employer and do not disclose the numbers. Keep the cards and receipts securely. Contact the card issuer through its official support route to explain the situation and ask about available options.
Retailer return policies and card restrictions vary, so do not assume the purchase can simply be reversed at the checkout. The important immediate step is to avoid turning an unshared card into a value transfer to the caller.
Tell the bank about the suspicious check even if the cards remain unused. The deposit issue still exists independently of whether the scammer obtained the card value.
If the codes or money have already been sent
Instead of asking only whether the deposit is available, say that a stranger sent the check for a job and instructed you to buy gift cards or send money elsewhere. Ask to speak with the team handling suspected check fraud. Keep the check details, deposit date, messages, and any outgoing receipts ready for the bank’s secure reporting channel. Ask what you should avoid doing while it investigates, how it will contact you, and whether there is a case reference to retain. A screenshot of an available balance cannot answer those questions, and the recruiter should not participate in that call.
Contact the gift-card issuer or payment provider immediately. Provide the receipt, amount, time, and relevant references through its secure support process. Ask whether any funds remain protectable; do not assume recovery is impossible, but do not accept promises that it is guaranteed.
Also speak with your bank about the check and the account balance. The final outcome depends on the transaction and applicable rules. Avoid taking a stranger’s advice to conceal the deposit’s origin or invent a different explanation for the payment.
Report suspected fraud to ReportFraud.ftc.gov and the recruitment platform involved. The FTC’s recovery guide provides payment-specific next steps.
Separate embarrassment from the next useful action
A job offer can arrive when extra income matters urgently. That makes the promise attractive; it does not make the recipient responsible for a stranger’s deception. The practical priority is to stop additional movement of money and document what happened accurately.
Our guide to recruiter texts that become payment requests covers a different opening to a similar problem. In both cases, the job story must not replace verification of the employer and the transaction.
A useful final rule is specific: a stranger’s check is not permission to send money or gift-card codes elsewhere. Ask the bank about the suspect deposit, and verify the employment relationship before doing anything with the funds.
Found a factual error or a source that has changed?
Send a correction →