The job equipment check looks cleared. That does not make the money yours
A new employer sends a check and asks you to buy equipment from its supplier. The dangerous assumption is that an available balance proves the check is good.
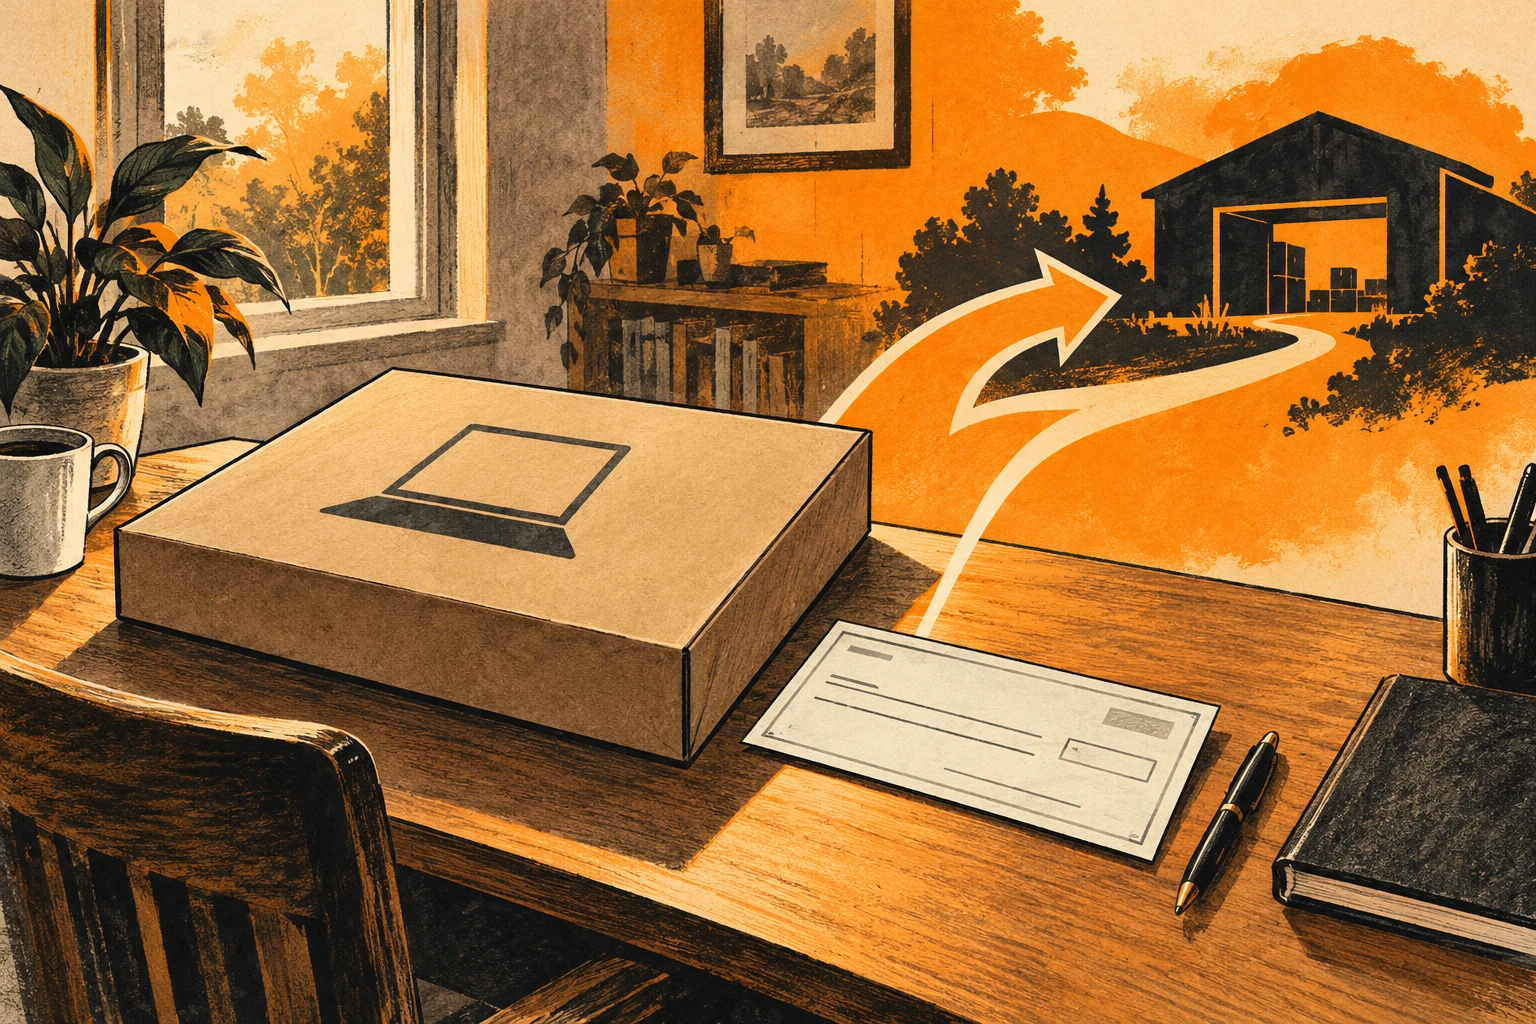
The offer feels like progress. After applications, interviews and waiting, a company says you are hired. It sends a check for a laptop and other equipment, then tells you to purchase everything from a designated supplier. Your banking app shows the deposit. The recruiter says that means you can get started.
The crucial distinction is money being available in an account versus the underlying check being genuine and finally resolved. Treating those as the same event can turn a fake employer’s equipment request into a payment made with your own money.
If you have deposited the check, do not panic or quietly move the funds elsewhere. Contact your bank through its established channel, explain that the deposit may be connected to employment fraud, and ask what to do. Do not send a refund to the supposed employer on your own.
The transaction, drawn without the job story
Remove the friendly recruiter, the onboarding paperwork and the company logo. What remains is a stranger sending you a check and directing you to move money to someone else. The check is the justification for the outgoing payment; the outgoing payment is the step the other party wants completed.
A check whose reliability is not established.
A supplier payment, refund or gift-card purchase.
You may send usable money before the deposit problem is discovered.
This does not mean every employer reimbursement is fraudulent. Legitimate organizations buy equipment and reimburse expenses. The question is why a newly contacted applicant is being used as a payment intermediary, why the supplier is prescribed, and whether the employment relationship can be verified outside the conversation.
The FTC’s fake-check guidance explains that banks can make deposited funds available before a counterfeit or otherwise bad check is discovered. It also describes job-related requests to use a deposit for purchases or payments. The apparent balance is therefore not the independent assurance a recruiter may claim it is.
Words that create false certainty
People use “cleared,” “posted,” “available” and “accepted” loosely. A recruiter may choose the strongest-sounding word, while your bank’s interface uses a different one. Do not build a decision around your interpretation of a status label.
Ask the bank a concrete question: “I received this check from a person claiming to hire me, and they want me to send money to their equipment supplier. I suspect a scam. What does the current status mean, and what should I do with the deposit?” That gives the bank the relevant context.
A generic question such as “Can I spend my balance?” may not convey the problem. Nor should you assume that waiting a fixed number of days creates a universal safe period. Check types, payment systems, returns and account terms vary. The bank needs to evaluate the actual deposit and circumstances.
| Phrase you hear | What to clarify |
|---|---|
| “The bank accepted it” | Was the deposit received, or has its legitimacy been established? |
| “The funds are available” | Could the account still be debited if the check is returned? |
| “Our supplier needs payment today” | Why is a new employee funding this supplier personally? |
| “Return the unused balance” | Why should you create a separate outgoing transaction? |
| “Use this payment app” | What protection applies, and why is normal procurement bypassed? |
The table is a conversation aid, not a banking-law summary. Get the account-specific answer from the institution, and keep a record of the advice you receive.
Verify the employer without asking the impersonator
Find the company’s genuine careers page and independently sourced contact details. Ask whether the role, recruiter and equipment process exist. A real company’s name on a check or offer letter is not proof that the sender represents it.
If you applied through a job platform, review the listing inside your account and report inconsistencies through the platform’s support route. Do not assume the platform’s presence means every subsequent email or chat is authorized. The conversation may have moved to a different address or account.
A lengthy interview is not conclusive either. Time spent with an applicant can be part of the persuasion. Conversely, a brief hiring process does not by itself prove fraud. Evaluate the payment request and the independently confirmed employment relationship, not just the amount of effort the recruiter appears to have invested.
The FTC’s job-scam overview covers fake employers and requests that turn the job seeker into the payer. Use it as background, then check the specific organization. You do not need to accuse the recruiter to pause a transaction that has not been verified.
Three moments, three different responses
The check has arrived but you have not deposited it
Do not deposit it merely to see whether the bank notices a problem. Preserve the message and check details privately, verify the employer independently, and contact your bank if you need guidance about handling the document. Avoid uploading the full check to a public scam forum.
You can decline the equipment arrangement without surrendering all hope of employment. Tell the independently verified organization that you need its normal procurement or reimbursement procedure. If the only person who can explain that procedure is the suspicious recruiter, the verification is incomplete.
You deposited it but have not sent money
Stop further movement and contact the bank. Explain the suspected fraud, the deposit amount and the requested outgoing payment. Do not withdraw the funds, shift them to another account or send them back to the recruiter to “undo” the situation. Those steps can add transactions without resolving the original deposit.
Keep ordinary account needs in mind. If rent or bills are due, ask the bank how the disputed deposit affects your actual available resources. Do not silently count the check as income while hoping it will turn out well.
You already paid the supplier
Tell both the bank and the outgoing payment provider promptly. Identify the payment method, recipient, amount and time. Ask whether a stop, recall or dispute is possible, without assuming that it will succeed. Preserve receipts and any delivery promises.
Do not pay another amount to release equipment, cancel the order or recover the deposit unless a verified institution confirms a legitimate basis. A story can evolve quickly once you question it. The next charge may be framed as the final administrative step needed to solve the first problem.
The supplier is part of the verification problem
A website selling laptops may look ordinary. A person may answer a support chat and issue an invoice. That does not prove the supplier is independent of the fake employer. If both contacts came from the same recruiter, they are not two separate confirmations.
Ask why the employer cannot order the equipment directly, whether the supplier is named in an independently verified company policy, and whether you are being asked to use an unusual payment route. You are not expected to investigate the supplier’s ownership structure. You are entitled to avoid becoming its payer before the arrangement is established.
Do not be reassured solely by tracking information. A parcel record does not establish that the expected equipment was purchased, that the sender is legitimate or that the incoming check is good. Keep each claim tied to the evidence that can actually support it.
Onboarding documents create a second exposure
The money may be only part of the incident. Applicants can also send identity documents, tax details, bank information and signatures during fake onboarding. List exactly what you shared and through which channel.
For a genuine employer, sensitive onboarding should follow its verified process. For a suspected impersonator, seek the appropriate identity-protection guidance for your location and notify affected institutions as relevant. A check being returned does not automatically resolve copied identity information.
If you installed software for the interview or onboarding, mention that separately when obtaining technical help. Do not let the recruiter provide the cleanup tool or remote-access session. The person whose instructions created the risk should not control the response.
A calmer way to tell someone close to you
You might feel embarrassed because the job was important or because you announced it to family. The useful sentence is factual: “The employer’s equipment-payment process may be fraudulent. I am stopping payments and speaking with the bank.” You do not need to defend every earlier decision before taking the next one.
If you are supporting someone else, help them gather the chronology and reach verified contacts. Avoid demanding that they confront the recruiter or continue the conversation to obtain a confession. More interaction can expose more information and delay the bank report.
This pattern differs from a task job that demands a deposit. Here, the scam may appear to pay you first. In both cases, the decisive moment is being asked to put your own money at risk for an unverified employment promise.
Keep the boundary after the incident
A job offer should be evaluated as employment, not as an opportunity to move a stranger’s funds. Do not treat a generous equipment allowance as income until the relationship and payment arrangement are established. Do not create a separate refund merely because someone says the deposit was an error.
For a related payment-correction trap, see unexpected Venmo payments. The systems differ, but the useful question is similar: should this problem be corrected by the provider handling the original transaction rather than by a new payment you initiate?
Sources: FTC fake-check guidance and FTC job-scam guidance. This article is U.S.-focused general education, not an account-specific determination of liability or recovery rights.
Found a factual error or a source that has changed?
Send a correction →